What should I do after a hailstorm damages my roof?
Write down the date, photograph hail and any dents on cars, gutters and patio furniture, and keep any leak contained. Get a roof inspection before you file, so you know there is covered damage. Then file with your insurer within the time your policy allows, and never sign with a contractor who offers to cover your deductible.
The evidence is easiest to collect on the day of the storm
Hailstones melt within the hour, and the dents they leave on a car or a grill lid are the easiest proof of size you will ever get. A photo of a few stones next to a coin or a ruler, and of dents on soft metal around the yard, helps an adjuster understand what the roof went through before anyone climbs a ladder.
Note the date and the approximate time. Storm reports from the National Weather Service and hail-tracking services are organized by date, and a claim will reference one. If several storms came through in the same spring, knowing which one did the damage matters.
Do not climb onto the roof yourself. Wet shingles are slick, and a hail-bruised roof looks perfectly normal from a ladder in most cases.
Damage that does not leak is still damage
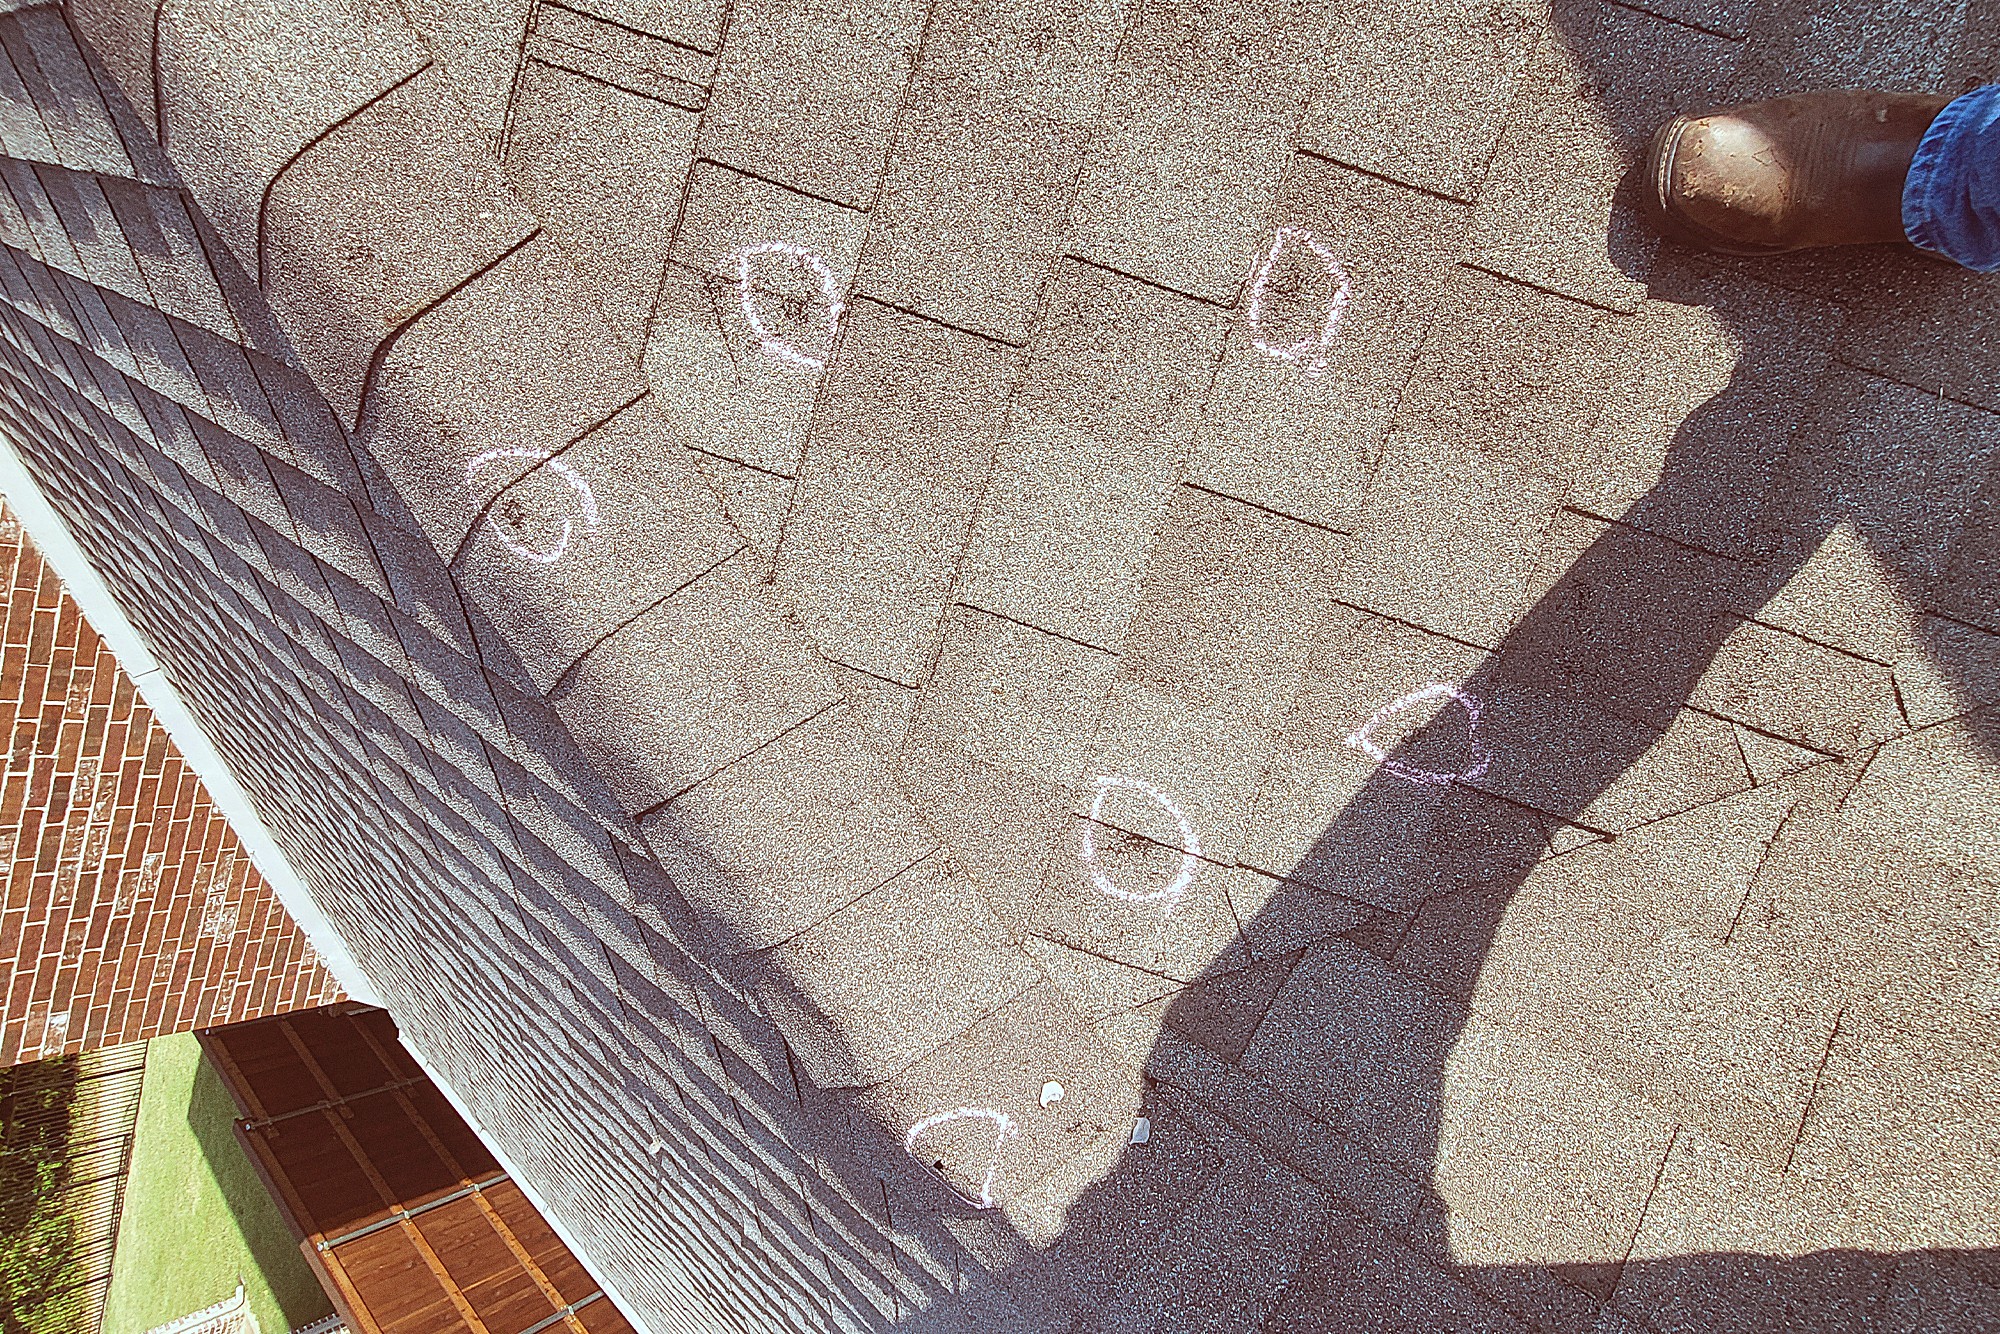
Most hail damage to an asphalt shingle roof does not leak straight away. The hit knocks granules loose and bruises the mat, and the shingle carries on shedding water until the sun breaks that spot down, sometimes a year or more later. A roof that is dry the day after the storm can still have a valid claim.
On the ground, the signs are indirect. Granules piling up where the downspouts empty, dents on gutters, vents and window screens, and torn screens on the side the storm came from all suggest the roof was hit too.
Inspect first, then call the insurance company
It is tempting to call the insurer the minute the storm passes. The problem is that a claim is recorded when it is opened, even if the adjuster finds no covered damage. An inspection first tells you whether there is damage and roughly how much, and whether it is likely to be worth a claim once your deductible comes off.
Most homeowners policies set a deadline for reporting storm damage, and the policy language varies. Check yours, or ask your agent, so a slow spring does not run the clock out.
When you do file, the adjuster will schedule an inspection. Having the roofer who inspected your roof there at the same time is the simplest way to make sure both people are looking at the same damage.
The offers to walk away from
After a big storm, door knockers arrive within days. Some are legitimate. The warning signs are the same every year: a contract you are asked to sign on the spot, a promise to pay or waive your deductible, and a company with no local address.
Texas law makes the homeowner responsible for paying the deductible. A contractor who offers to absorb it is breaking that law and putting your claim at risk. Take a card, check the company, and book an inspection on your own schedule.
Related questions
How long do I have to file a hail claim in Texas?
It depends on your policy. Many set a limit measured from the date of the storm, commonly a year or two. Read the policy or ask your agent.
Will one hail claim raise my insurance rates?
Weather claims are generally treated differently from claims caused by the homeowner, but every carrier handles it its own way. Your agent can tell you how yours does.